
By: Anand Melwani
Two years ago, everyone in commercial real estate made the same bet: rates had peaked, and the inevitable march downward would begin. It was a beautiful story and comforting to repeat while watching your deals pencil. The Fed was done hiking. Relief was coming.
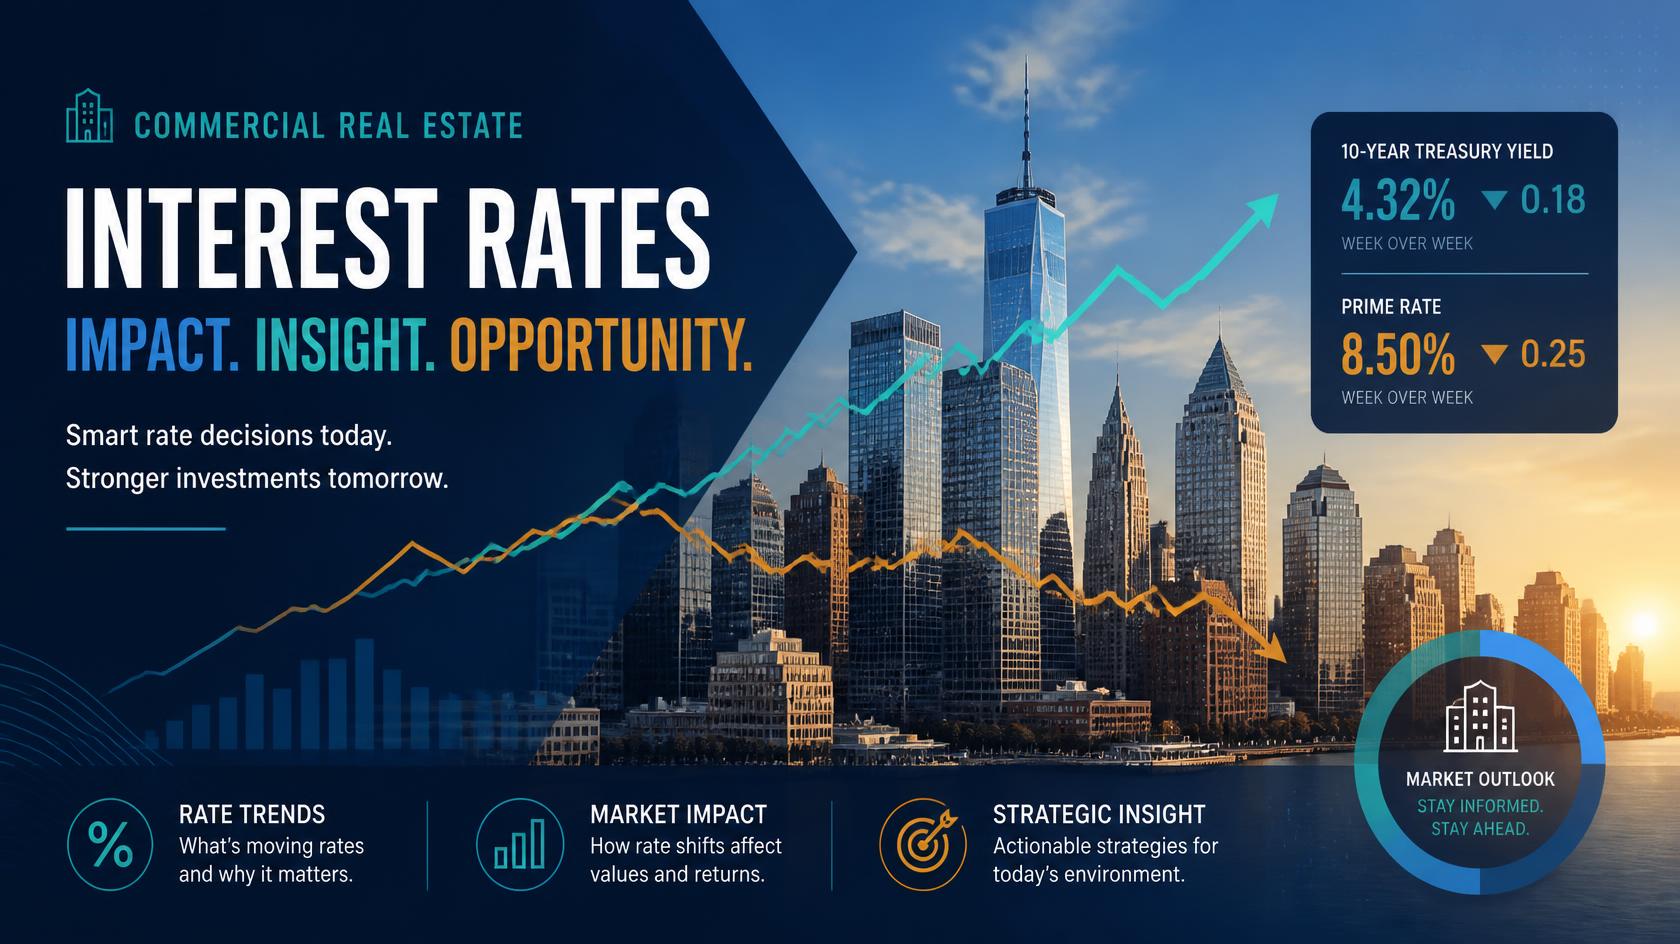
Instead,we're here. Staring at commercial mortgage rates at 5.70%-6.63% depending onloan type. Fed officials are signaling they might hike again this month, and marketsare pricing rate increases through August 2027. The consensus forecast foryear-end 2026 puts us at 3.6%-4.1% on Fed funds.
Not lower. Higher.
The Math Is Brutal. The Timing Is Worse
Commercial mortgage rates have essentially doubled since 2023. If you locked a deal at 3.5% in late 2021, you're looking at a new rate above 6% on refinance. That's not a tweak to your underwriting. That's a full reset.
The maturity wall hits even harder. Nearly $1 trillion in commercial real estate debt is maturing across 2025-2026. Loans that were written at 4.59%-4.91% average rates are coming due and resetting into a 6%+ environment. That's a rate jump of 100-150 basis points per loan.
Ona $50 million deal, that's an extra $500,000-$750,000 in annual debt service.On a $250 million portfolio, you're looking at a $2.5-3.75 million annual hit.
In NYC specifically, where cap rates haven't moved nearly as much as debt costs, this math is ferocious. Your pro forma assumed 4.5%. You're now competing for capital at 6.5%. That changes everything about value, development feasibility, and risk pricing.
What The Consensus Gets Wrong
The prevailing view right now is that the Fed has done its job and we're in a holding pattern. Inflation is moderate. The job market is soft. A rate cut will come—probably in late 2026 or early 2027.
Thisstory ignores three problems:
1. Inflation is stickier than we'd like to admit. Long-term Treasury yields have drifted higher on their own, independent of Fed policy. Energy costs remain elevated due to geopolitical risk. Wage inflation in construction and services is real. The Fed may be stuck.
2. Commercial real estate debt maturity wall hit hardest in late 2026 and 2027. As properties reset and capital structures break, you're going to see forced sales, mark-to-market losses, and a reset of risk premiums. The Fed won't want to cut into that kind of stress.
3. Market participants are priced for a September rate hike, not a cut. Even if the Fed pauses, that's a win that nobody expects, and it still leaves us holding expensive capital for the foreseeable future.
The real baseline: Rates stay higher than the pre-2022 normal. They may go up or sideways, but they are not coming down. Anyone underwriting a deal in NYC in 2026 based on a 4% interest rate is not serious.
What This Means for Your Deal
If you have debt maturing in the next 18 months, move now or move last year. Waiting is a tax. Every month you delay your basis points on refinance, and you might not have capacity to do a deal at 6.5% that penciled at 4.5%.
Development in NYC requires a different capital stack now. Equity returns assumptions need to be 15%+ instead of 10-12%. Fixed-rate debt is no longer a luxury, it's a necessity. Any floating-rate exposure is a tail risk you do not want to carry.
Asset quality is the new story. In a 6.5% world, you can't underwrite a mediocre building on the assumption of rent growth and cap rate compression. You need cash flow. You need stabilized tenancy. You need a reason to hold it beyond "eventually the market will reward this."
Commercial Waste Zones and development site strategy matter more. In a high-cost-of-capital environment, the projects that pencil are the ones with real scarcity value - air rights, zoning optionality, strategic infilllocations. Generic assets get squeezed out.
The uncomfortable truth: The deals that worked in 2021 are not coming back. Cap rate expansion +rate hikes is a two-step down for values. Some owners won't make it through the cycle. Others will recapitalize or refinance at painful terms. The property markets are going to reset, and it will do so in a world where 6%+ cost of capital is the new baseline.
Want to talk through your deal?
If you're evaluating a site, planning development, or trying to figure out which path your project takes, we have the roadmap.
Info@landairnyc.com
Anand Melwani
Partner and Co-Founder, Landair Advisors
We specialize in development sites, air rights, and investment sales across the five boroughs.
Landair Advisors | 224 W 30th Street, Suite 301, New York, NY 10001 | (646) 559-4700
© 2026 Landair Advisors. All rights reserved.